 Weather
 Locations
 Careers
 Login

Lemon and orange updates
U.S. orange production expected to fall.
USDA forecasts U.S. orange production to fall 2.9% for the 2026/27 season, driven by declines in Florida. Florida’s crop is expected to fall 23% year over year to 10 million boxes, with industry sources pointing to winter freeze damage as a key contributor. The decline comes amid a longer-term contraction in Florida’s citrus industry, including fewer bearing trees and continued pressure from citrus greening. California production is moving in the opposite direction, with USDA forecasting a roughly 2% increase to 50.5 million boxes. The California Valencia season is now effectively complete, and attention is shifting toward the developing navel crop. Despite tighter U.S. and Brazilian orange supplies, orange juice markets remain under pressure from softer demand and elevated inventories.
USDA forecasts higher California lemon production in 2026/27, although reports suggest conditions vary by growing district. A lighter crop is reported in the desert growing region, while higher year-over-year volume is expected in the Central Valley. Fruit sizing and quality are reportedly good overall, although some wind scarring and cosmetic issues have been reported in the desert region. Import competition continued to weigh on lemon markets through October. While demand reportedly improved late in the month, prices have yet to respond.
Profitability
September 16, 2026Lemons: Breakeven profitability - Neutral 12-month outlook
Oranges: Slightly profitable - Neutral 12-month outlook
Relatively weak markets along with a surge in South American imports are pressuring lemon prices.
Orange prices have been impacted by large fruit sizing, quality issues and lower juice prices. Despite these challenges, most producers remain slightly profitable.
Domestic markets make up the vast majority of lemon and orange demand, with exports only accounting for about 11% of total production. The largest foreign markets include Canada, South Korea, Mexico, Japan, and to a much lesser extent, Hong Kong. Lemon and orange imports have increased significantly over the last decade and make up 17% of total domestic supply, a relatively high amount compared to other specialty crops. Increased plantings coupled with low labor costs and minimal trade barriers have enabled citrus growers in Central and South America to compete in U.S. markets.
Lemon production, exports and imports
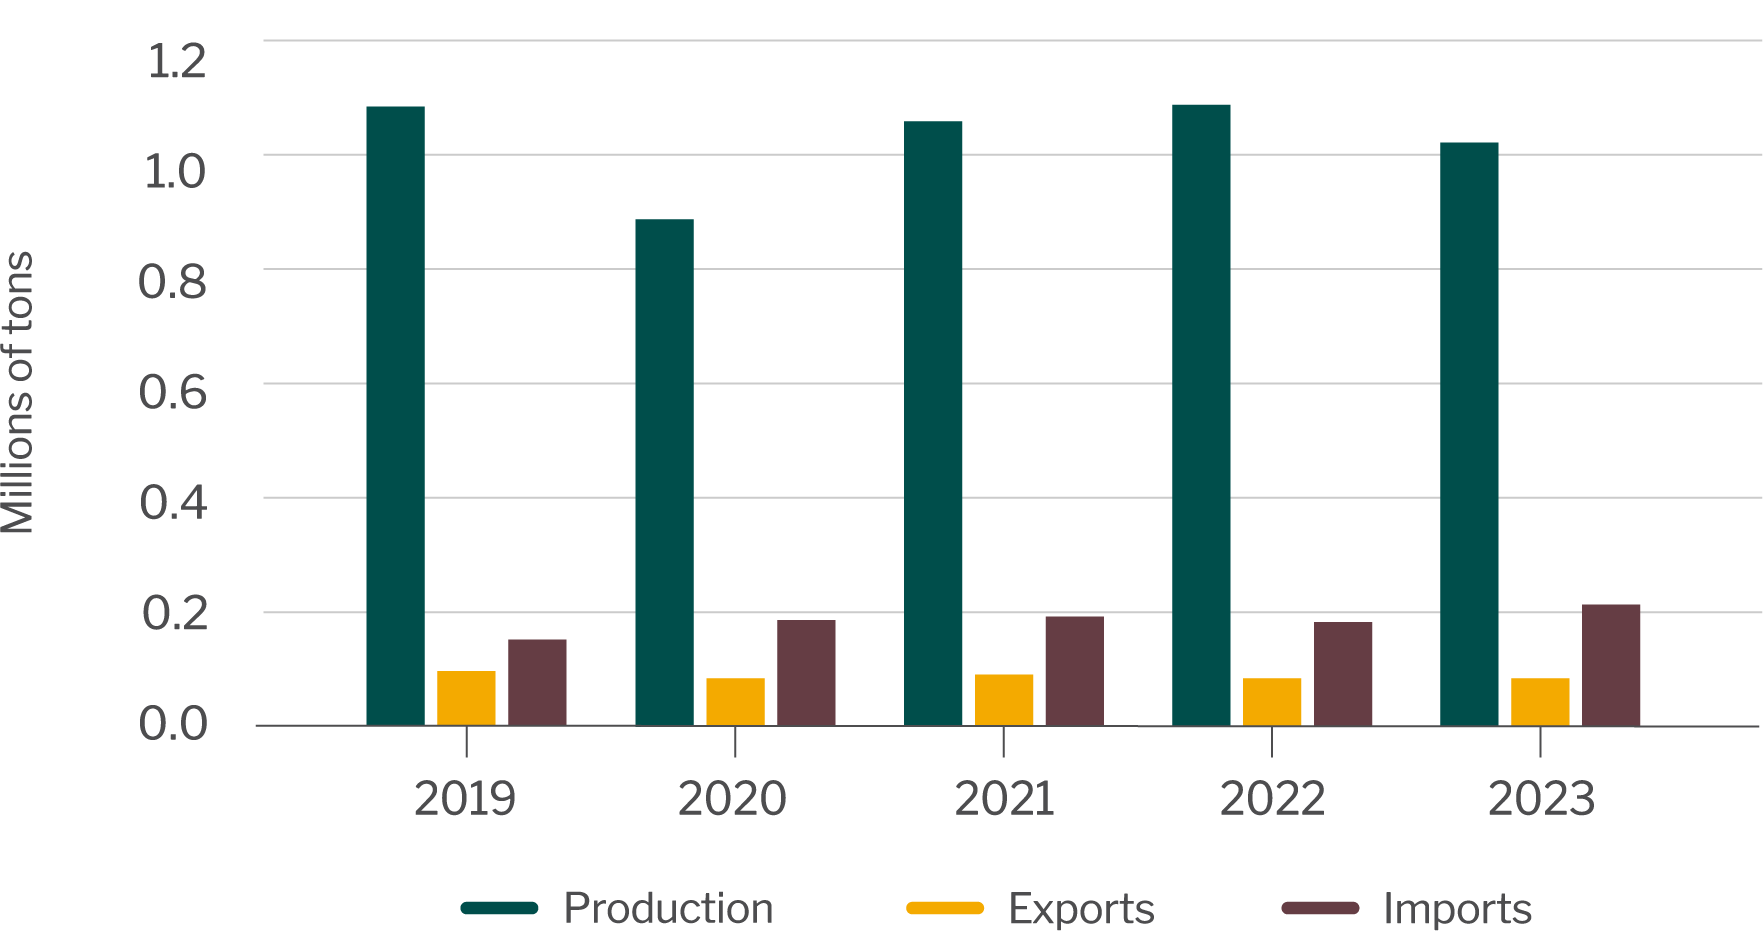
USDA Citrus Fruits Summary. U.S. Census Bureau. Crop year is from August to July.
Orange production, exports and imports
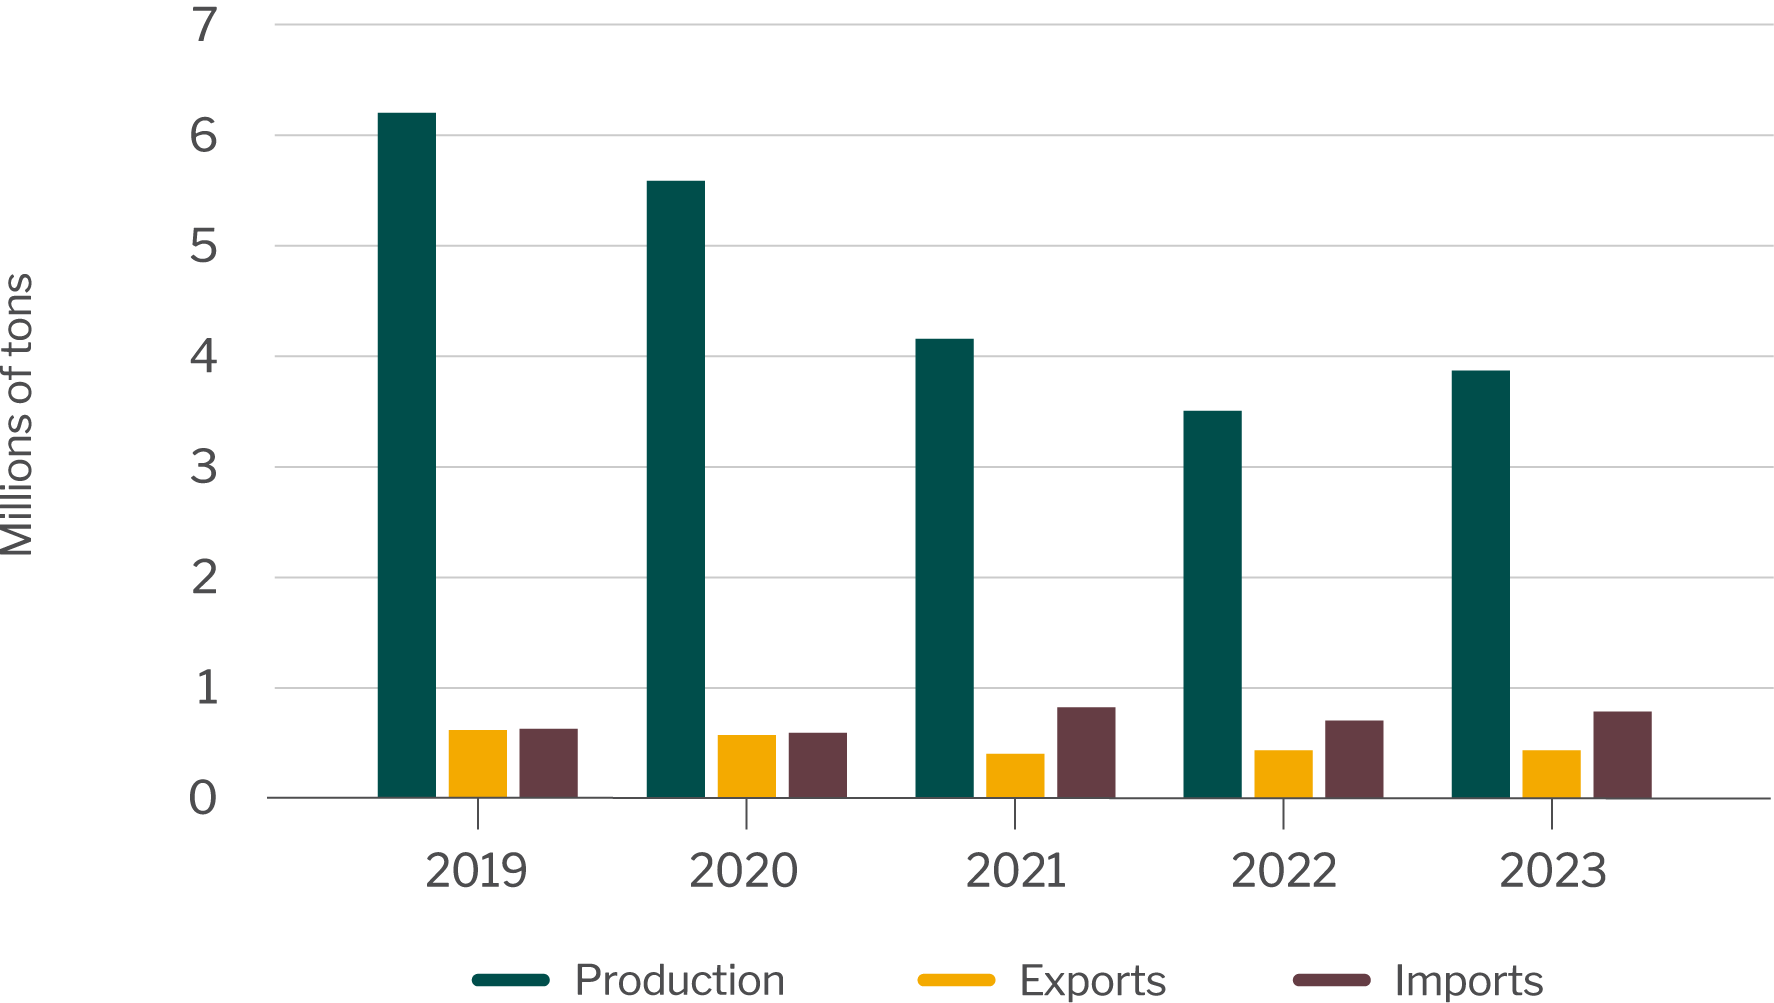
USDA Citrus Fruits Summary. U.S. Census Bureau. Crop year is from October to September.
Tariff tracker - Tariff rates applied to U.S. trade partners are consistenly updated to reflect policy changes. The World Trade Organization (WTO) tracks duties and tariffs on lemons and oranges. For your convenience, the following links will take you to tariff data for South Korea (fresh oranges and mandarins/tangerines/satsumas) and Japan (fresh oranges and mandarins/tangerines/satsumas). Citrus fruits are currently exempt from tariffs with Canada under the United States-Mexico-Canada Agreement (USMCA), but please refer to the U.S. Trade Representative website for up-to-date information. WTO also tracks rates for lemon imports and orange imports to the U.S. Please consult with a trade lawyer or professional for detailed and up-to-date insights on tariff rates and their application to lemons and oranges.
For guidance on interpreting duty and tariff rates, please refer to our Tariff Guide.
Lemon and orange updates
U.S. orange production expected to fall.
USDA forecasts U.S. orange production to fall 2.9% for the 2026/27 season, driven by declines in Florida. Florida’s crop is expected to fall 23% year over year to 10 million boxes, with industry sources pointing to winter freeze damage as a key contributor. The decline comes amid a longer-term contraction in Florida’s citrus industry, including fewer bearing trees and continued pressure from citrus greening. California production is moving in the opposite direction, with USDA forecasting a roughly 2% increase to 50.5 million boxes. The California Valencia season is now effectively complete, and attention is shifting toward the developing navel crop. Despite tighter U.S. and Brazilian orange supplies, orange juice markets remain under pressure from softer demand and elevated inventories.
USDA forecasts higher California lemon production in 2026/27, although reports suggest conditions vary by growing district. A lighter crop is reported in the desert growing region, while higher year-over-year volume is expected in the Central Valley. Fruit sizing and quality are reportedly good overall, although some wind scarring and cosmetic issues have been reported in the desert region. Import competition continued to weigh on lemon markets through October. While demand reportedly improved late in the month, prices have yet to respond.
Profitability
September 16, 2026Lemons: Breakeven profitability - Neutral 12-month outlook
Oranges: Slightly profitable - Neutral 12-month outlook
Relatively weak markets along with a surge in South American imports are pressuring lemon prices.
Orange prices have been impacted by large fruit sizing, quality issues and lower juice prices. Despite these challenges, most producers remain slightly profitable.
Domestic markets make up the vast majority of lemon and orange demand, with exports only accounting for about 11% of total production. The largest foreign markets include Canada, South Korea, Mexico, Japan, and to a much lesser extent, Hong Kong. Lemon and orange imports have increased significantly over the last decade and make up 17% of total domestic supply, a relatively high amount compared to other specialty crops. Increased plantings coupled with low labor costs and minimal trade barriers have enabled citrus growers in Central and South America to compete in U.S. markets.
Lemon production, exports and imports
USDA Citrus Fruits Summary. U.S. Census Bureau. Crop year is from August to July.
Orange production, exports and imports
USDA Citrus Fruits Summary. U.S. Census Bureau. Crop year is from October to September.
Tariff tracker - Tariff rates applied to U.S. trade partners are consistenly updated to reflect policy changes. The World Trade Organization (WTO) tracks duties and tariffs on lemons and oranges. For your convenience, the following links will take you to tariff data for South Korea (fresh oranges and mandarins/tangerines/satsumas) and Japan (fresh oranges and mandarins/tangerines/satsumas). Citrus fruits are currently exempt from tariffs with Canada under the United States-Mexico-Canada Agreement (USMCA), but please refer to the U.S. Trade Representative website for up-to-date information. WTO also tracks rates for lemon imports and orange imports to the U.S. Please consult with a trade lawyer or professional for detailed and up-to-date insights on tariff rates and their application to lemons and oranges.
For guidance on interpreting duty and tariff rates, please refer to our Tariff Guide.
IN THIS SECTION

Lemon and Orange Industry Perspective
View the latest AgWest Lemon and Orange Industry Perspective.
Learn more