Weather
 Locations
 Careers
 Login

Potato updates
Improved supply-demand balance.
The 2026 potato crop is expected to be smaller than 2025 due to reduced acreage and weather-related yield challenges in several major growing regions. In Idaho, summer heat pressured yields, while lower planted acreage further reduced open-market potato supplies. Washington's Columbia Basin was one of the few production areas to benefit from favorable growing conditions, resulting in strong yields and good crop quality.
Tighter supplies have supported stronger prices compared to a year ago. Russet shipping-point prices remain well above 2025 levels, reflecting improved grower bargaining power and expectations for a smaller crop. As a result, grower return indices have strengthened significantly from year-earlier levels. International trade continues to provide additional support. U.S. fresh potato exports reached record levels during the 2025-26 marketing year, driven largely by strong demand from Mexico and Canada.
Looking ahead, export demand is expected to remain an important outlet for U.S. production, although expanding Canadian production could increase competition in certain fresh potato markets during the coming season. In the Pacific Northwest, processing potato supplies are expected to be better aligned with demand than in recent years, reducing the likelihood of large surplus volumes entering the open market.
Profitability
September 16, 2026Potatoes (contracted): Slightly profitable - Neutral 12-month outlook
Potatoes (uncontracted): Slightly unprofitable - Bullish 12-month outlook
Contracted potatoes are expected to remain slightly profitable as processor contracts provide stable pricing. Water shortages may result in a smaller crop.
Uncontracted potatoes remain slightly unprofitable as elevated input costs continue to pressure margins, although improving supply-demand balance and a smaller regional crop are expected to support stronger market prices moving forward.
The U.S. is the third-largest exporter of potatoes globally, followed by the European Union and Canada. Potato exports are generally categorized into five types: fresh, dehydrated, frozen, seed and chips. By value, frozen potatoes, most commonly in the form of french fries, make up the largest export category. The primary export destinations for U.S. potato products are Mexico, Japan, Canada and South Korea, which together account for 72% of all exports. Despite this, the U.S. imports more potatoes than it exports. This trade imbalance is typical for vegetables, as the U.S. often runs a trade deficit in most vegetable categories. Most imported potato products are sent to areas in the U.S. with limited potato production or consist of raw potatoes from Canada destined for U.S. processing plants.
Potato production, exports and imports
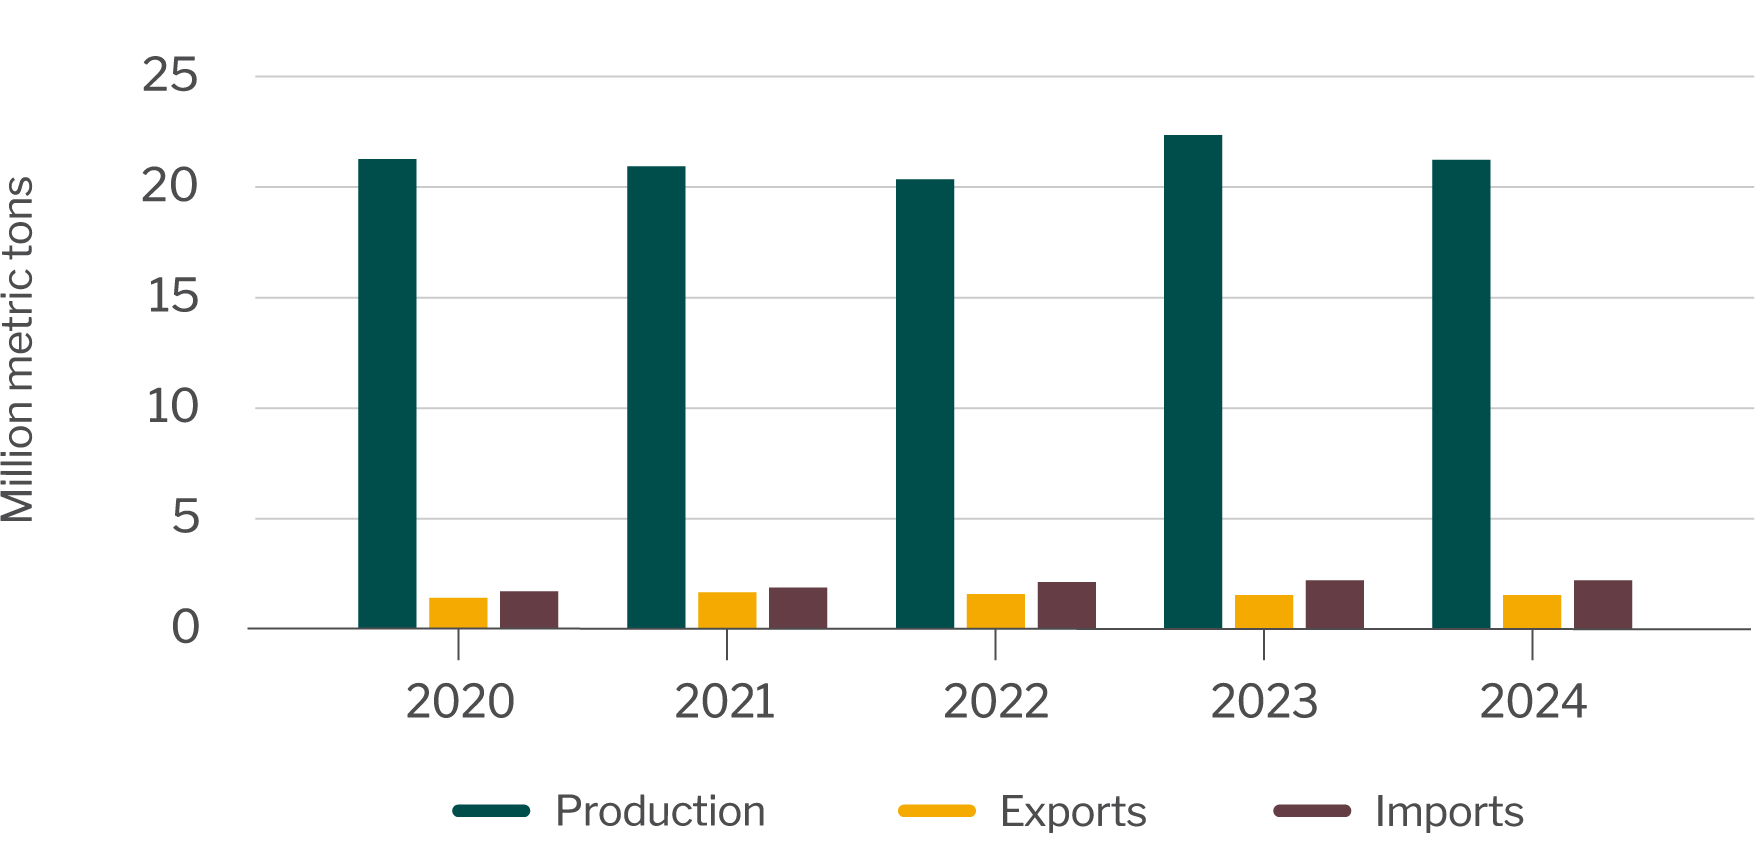
Source: USDA National Agriculture Statistics Service. U.S. Census Bureau.
Tariff tracker - Tariff rates applied to U.S. trade partners are consistenly updated to reflect policy changes. The World Trade Organization (WTO) tracks duties and tariffs on potato products. For your convenience, the following links will take you to tariff data on prepared, preserved, or frozen potato products (a leading U.S. export for the potato industry) for top markets including Japan and South Korea. Potato products are currently exempt from tariffs with Mexico and Canada under the United States-Mexico-Canada Agreement (USMCA), but please refer to the U.S. Trade Representative website for up-to-date information. WTO also tracks rates for potato imports to the U.S. Please consult with a trade lawyer or professional for detailed and up-to-date insights on tariff rates and their application to potatoes.
For guidance on interpreting duty and tariff rates, please refer to our Tariff Guide.
Potato updates
Improved supply-demand balance.
The 2026 potato crop is expected to be smaller than 2025 due to reduced acreage and weather-related yield challenges in several major growing regions. In Idaho, summer heat pressured yields, while lower planted acreage further reduced open-market potato supplies. Washington's Columbia Basin was one of the few production areas to benefit from favorable growing conditions, resulting in strong yields and good crop quality.
Tighter supplies have supported stronger prices compared to a year ago. Russet shipping-point prices remain well above 2025 levels, reflecting improved grower bargaining power and expectations for a smaller crop. As a result, grower return indices have strengthened significantly from year-earlier levels. International trade continues to provide additional support. U.S. fresh potato exports reached record levels during the 2025-26 marketing year, driven largely by strong demand from Mexico and Canada.
Looking ahead, export demand is expected to remain an important outlet for U.S. production, although expanding Canadian production could increase competition in certain fresh potato markets during the coming season. In the Pacific Northwest, processing potato supplies are expected to be better aligned with demand than in recent years, reducing the likelihood of large surplus volumes entering the open market.
Profitability
September 16, 2026Potatoes (contracted): Slightly profitable - Neutral 12-month outlook
Potatoes (uncontracted): Slightly unprofitable - Bullish 12-month outlook
Contracted potatoes are expected to remain slightly profitable as processor contracts provide stable pricing. Water shortages may result in a smaller crop.
Uncontracted potatoes remain slightly unprofitable as elevated input costs continue to pressure margins, although improving supply-demand balance and a smaller regional crop are expected to support stronger market prices moving forward.
The U.S. is the third-largest exporter of potatoes globally, followed by the European Union and Canada. Potato exports are generally categorized into five types: fresh, dehydrated, frozen, seed and chips. By value, frozen potatoes, most commonly in the form of french fries, make up the largest export category. The primary export destinations for U.S. potato products are Mexico, Japan, Canada and South Korea, which together account for 72% of all exports. Despite this, the U.S. imports more potatoes than it exports. This trade imbalance is typical for vegetables, as the U.S. often runs a trade deficit in most vegetable categories. Most imported potato products are sent to areas in the U.S. with limited potato production or consist of raw potatoes from Canada destined for U.S. processing plants.
Potato production, exports and imports
Source: USDA National Agriculture Statistics Service. U.S. Census Bureau.
Tariff tracker - Tariff rates applied to U.S. trade partners are consistenly updated to reflect policy changes. The World Trade Organization (WTO) tracks duties and tariffs on potato products. For your convenience, the following links will take you to tariff data on prepared, preserved, or frozen potato products (a leading U.S. export for the potato industry) for top markets including Japan and South Korea. Potato products are currently exempt from tariffs with Mexico and Canada under the United States-Mexico-Canada Agreement (USMCA), but please refer to the U.S. Trade Representative website for up-to-date information. WTO also tracks rates for potato imports to the U.S. Please consult with a trade lawyer or professional for detailed and up-to-date insights on tariff rates and their application to potatoes.
For guidance on interpreting duty and tariff rates, please refer to our Tariff Guide.