 Weather
 Locations
 Careers
 Login

Forest product updates
Lumber markets soften.
Lumber markets softened through October as persistently high mortgage rates and weak housing activity weighed on demand. September U.S. housing starts declined 5% from August and 7% from a year earlier, while single-family permitting fell to its lowest level since March 2023. Builder confidence also declined to its lowest level since 2012, reflecting continued affordability pressures as 30-year mortgage rates remained above 7%. The Framing Lumber Composite fell to $473 by mid-October after reaching $535 in July, although prices remained about 22% above year-ago levels. Lumber supply remains relatively tight following mill closures, curtailments and reduced imports.
Northwest log markets remained relatively stable in October, with mill inventories generally adequate, and buyers purchasing logs but showing little urgency. Washington and Oregon markets were characterized by steady demand and limited price movement, although cedar prices have fallen sharply in recent months. Export activity remains subdued, with Japanese demand for Douglas-fir steady but below historical levels and only limited volumes moving to China and Korea. Markets for pulp logs, chips and mill residuals remain particularly challenged by excess supply and reduced pulp-mill demand, although restarting pulp capacity in Washington and British Columbia could provide some relief.
Profitability
September 16, 2026Forest product mills: Slightly profitable - Neutral 12-month outlook
Timberlands: Slightly profitable - Neutral 12-month outlook
Stable lumber demand along with falling domestic production and Canadian imports are supporting slightly profitable conditions.
Despite strong log inventories, mill demand in the Northwest remains steady and supportive of prices.
The U.S. housing market is the primary driver of forest products demand. Log and lumber exports play a relatively minor role, making up about 6% and 3% of total domestic production, respectively. On the West Coast, log producers have historically benefited from strong Japanese demand for high-quality grades. Following the Great Recession, demand from China increased significantly to support housing construction. These trends are reversing due to aging demographics and weakening economies. The Softwood Lumber Agreement sets the terms for Canadian lumber exports to the U.S., which make up about a quarter of total domestic supply.
Log production, exports and imports
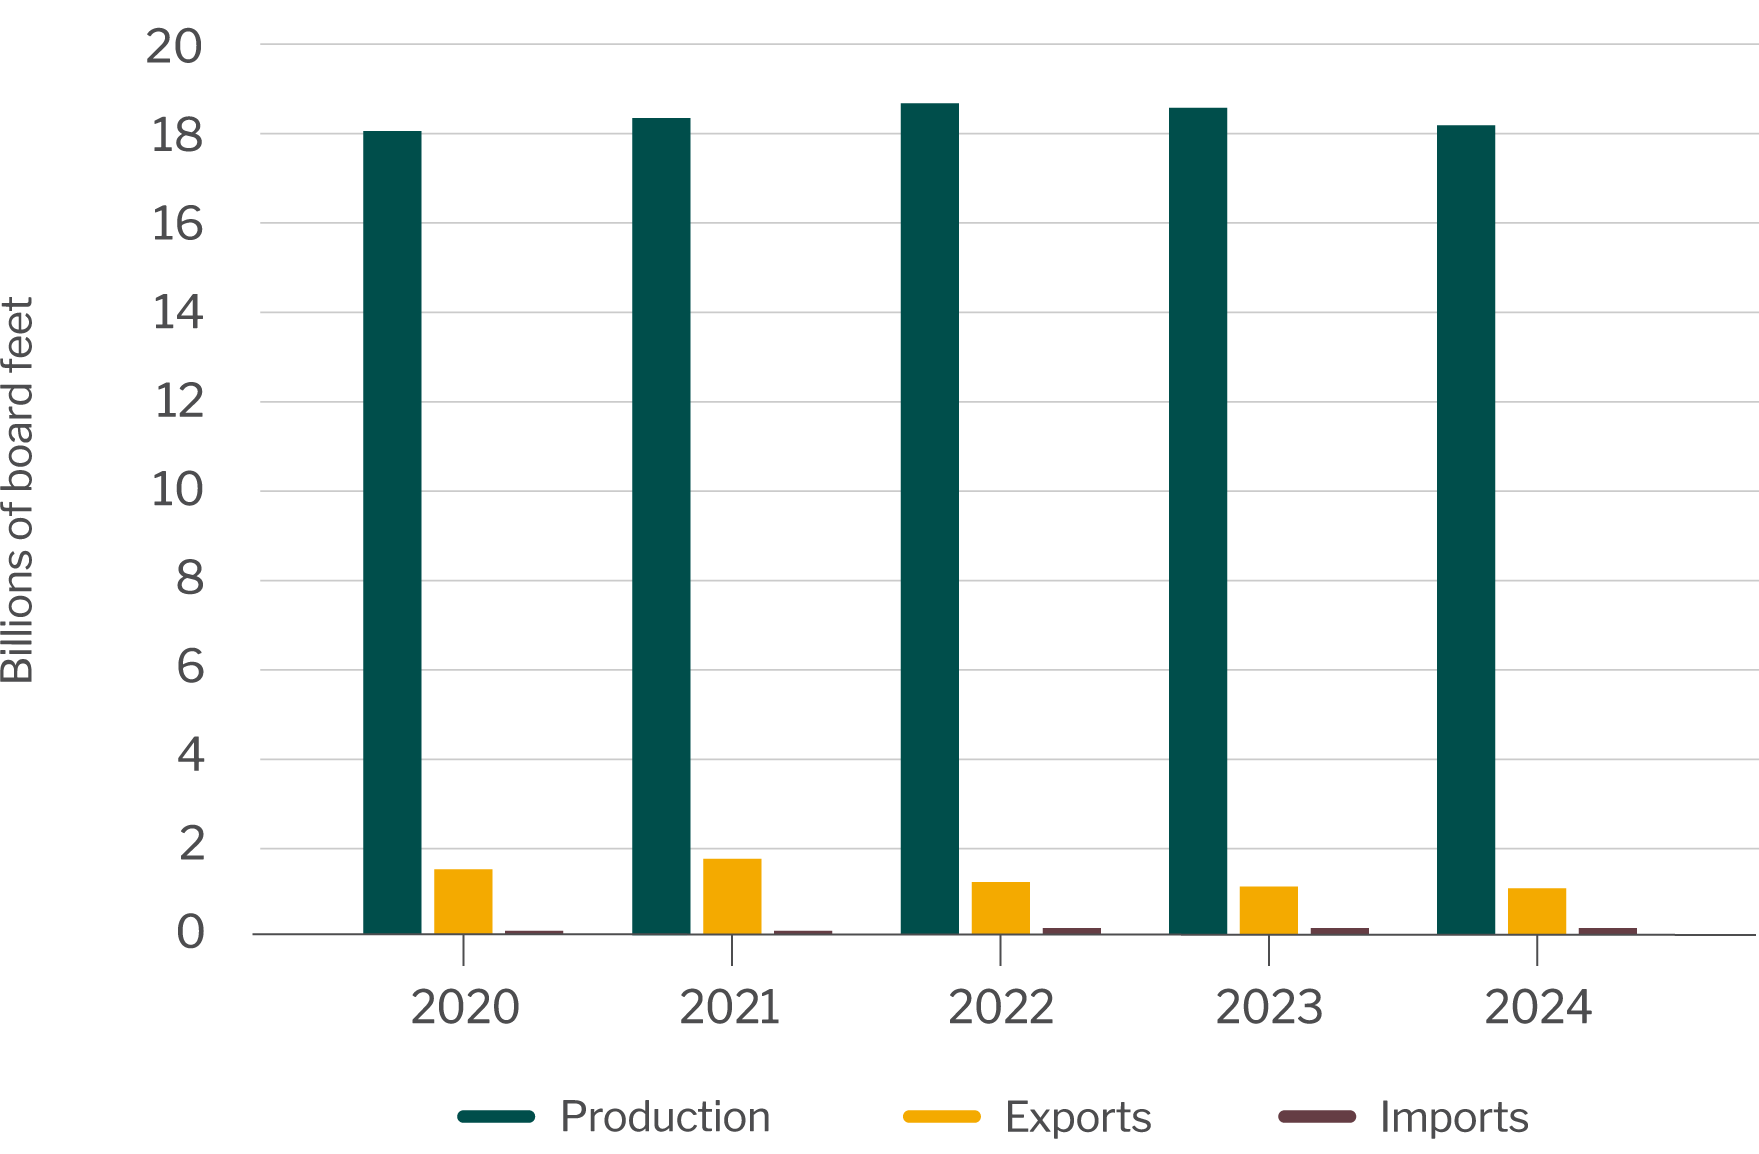
Forisk. U.S. Census Bureau. Production levels were calculated using region specific recovery rates. Trade data was converted using .22 thousand board feet per cubic meter.
Lumber production, exports and imports
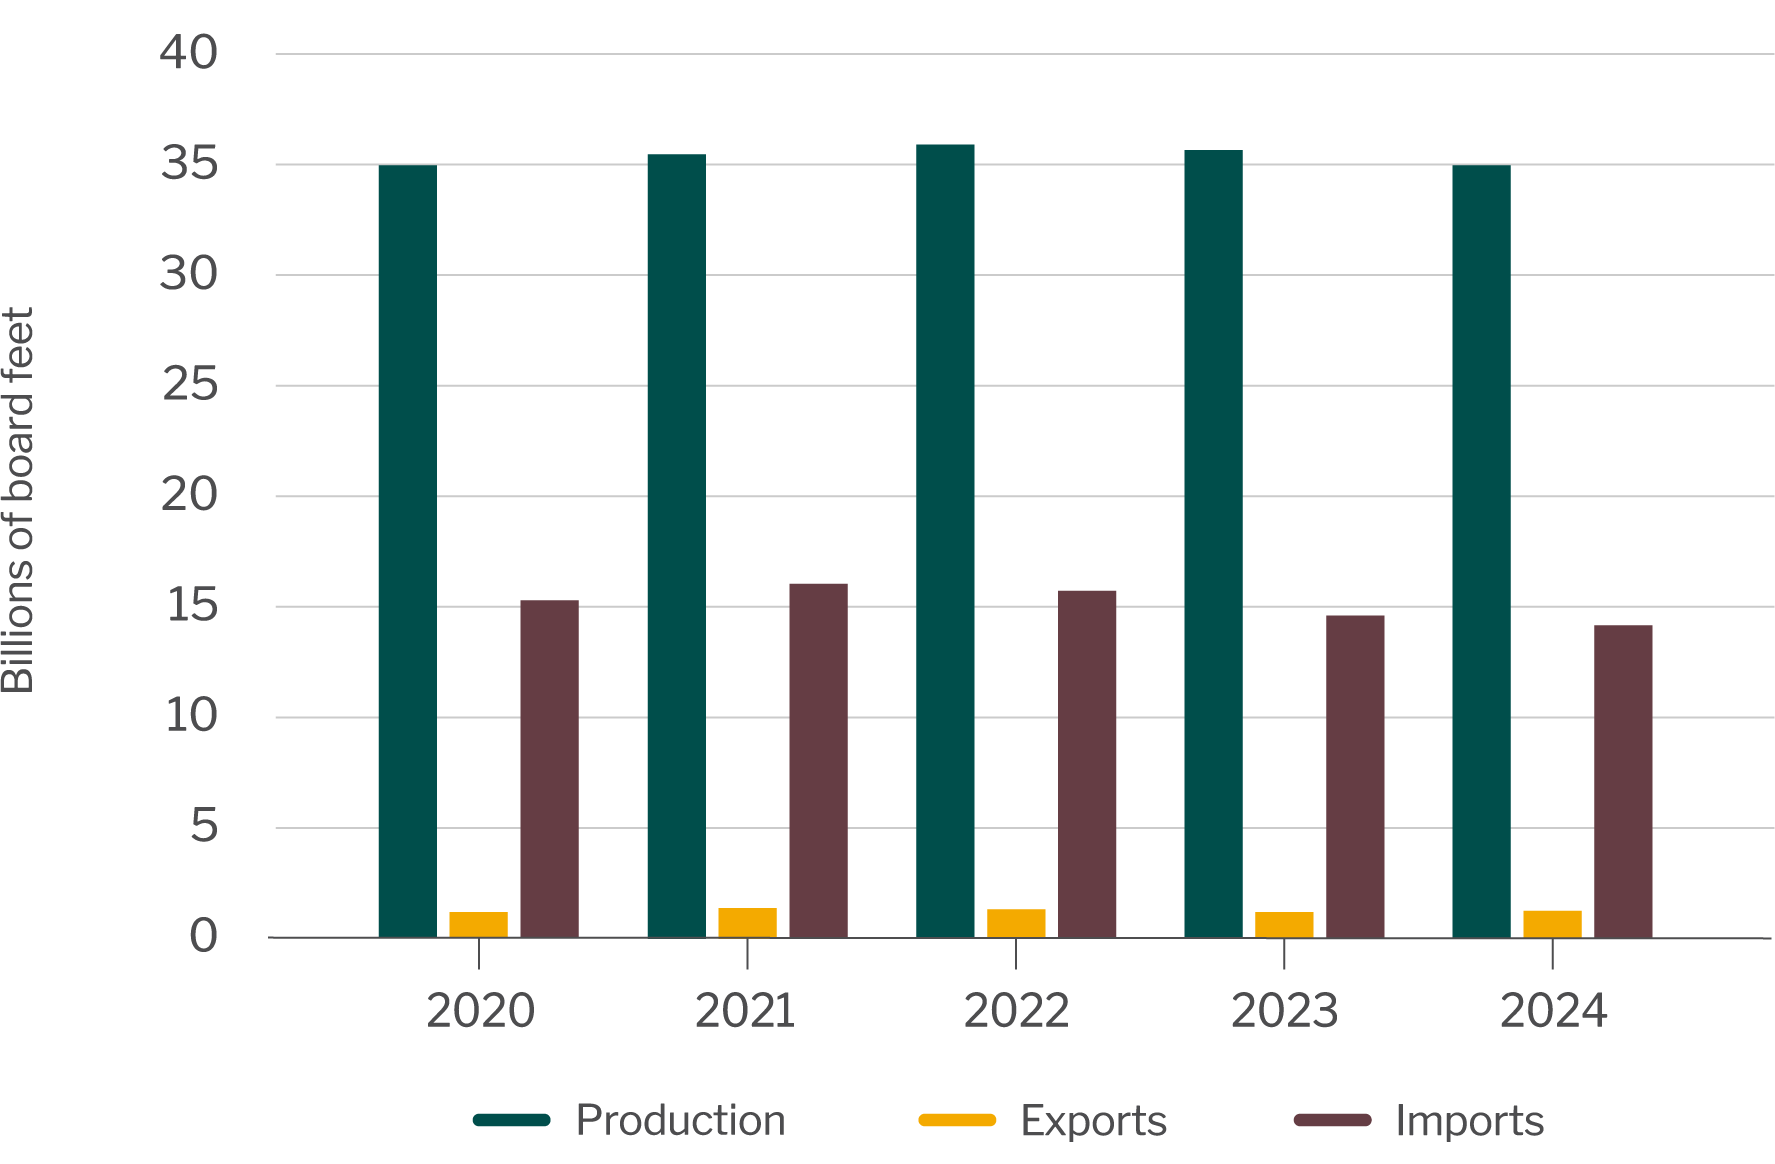
Forisk. U.S. Census Bureau. Trade data was converted using .452 thousand board feet per cubic meter.
Tariff tracker - Tariff rates applied to U.S. trade partners are consistenly updated to reflect policy changes. The World Trade Organization (WTO) tracks duties and tariffs on forest products. For your convenience, the following links will take you to tariff data for top markets, including Japan and Vietnam. Logs are currently exempt from tariffs for Canada under the United States-Mexico-Canada Agreement (USMCA), but please refer to the U.S. Trade Representative website for up-to-date information. The U.S. applies countervailing duties on Canadian lumber imports based on an annual review process (detailed information can be found at the Federal Register). Please consult with a trade lawyer or professional for detailed and up-to-date insights on tariff rates and their application to forest products.
For guidance on interpreting duty and tariff rates, please refer to our Tariff Guide.
Forest product updates
Lumber markets soften.
Lumber markets softened through October as persistently high mortgage rates and weak housing activity weighed on demand. September U.S. housing starts declined 5% from August and 7% from a year earlier, while single-family permitting fell to its lowest level since March 2023. Builder confidence also declined to its lowest level since 2012, reflecting continued affordability pressures as 30-year mortgage rates remained above 7%. The Framing Lumber Composite fell to $473 by mid-October after reaching $535 in July, although prices remained about 22% above year-ago levels. Lumber supply remains relatively tight following mill closures, curtailments and reduced imports.
Northwest log markets remained relatively stable in October, with mill inventories generally adequate, and buyers purchasing logs but showing little urgency. Washington and Oregon markets were characterized by steady demand and limited price movement, although cedar prices have fallen sharply in recent months. Export activity remains subdued, with Japanese demand for Douglas-fir steady but below historical levels and only limited volumes moving to China and Korea. Markets for pulp logs, chips and mill residuals remain particularly challenged by excess supply and reduced pulp-mill demand, although restarting pulp capacity in Washington and British Columbia could provide some relief.
Profitability
September 16, 2026Forest product mills: Slightly profitable - Neutral 12-month outlook
Timberlands: Slightly profitable - Neutral 12-month outlook
Stable lumber demand along with falling domestic production and Canadian imports are supporting slightly profitable conditions.
Despite strong log inventories, mill demand in the Northwest remains steady and supportive of prices.
The U.S. housing market is the primary driver of forest products demand. Log and lumber exports play a relatively minor role, making up about 6% and 3% of total domestic production, respectively. On the West Coast, log producers have historically benefited from strong Japanese demand for high-quality grades. Following the Great Recession, demand from China increased significantly to support housing construction. These trends are reversing due to aging demographics and weakening economies. The Softwood Lumber Agreement sets the terms for Canadian lumber exports to the U.S., which make up about a quarter of total domestic supply.
Log production, exports and imports
Forisk. U.S. Census Bureau. Production levels were calculated using region specific recovery rates. Trade data was converted using .22 thousand board feet per cubic meter.
Lumber production, exports and imports
Forisk. U.S. Census Bureau. Trade data was converted using .452 thousand board feet per cubic meter.
Tariff tracker - Tariff rates applied to U.S. trade partners are consistenly updated to reflect policy changes. The World Trade Organization (WTO) tracks duties and tariffs on forest products. For your convenience, the following links will take you to tariff data for top markets, including Japan and Vietnam. Logs are currently exempt from tariffs for Canada under the United States-Mexico-Canada Agreement (USMCA), but please refer to the U.S. Trade Representative website for up-to-date information. The U.S. applies countervailing duties on Canadian lumber imports based on an annual review process (detailed information can be found at the Federal Register). Please consult with a trade lawyer or professional for detailed and up-to-date insights on tariff rates and their application to forest products.
For guidance on interpreting duty and tariff rates, please refer to our Tariff Guide.
IN THIS SECTION

Forest Products Industry Perspective
View the latest AgWest Forest Products Industry Perspective
Learn more